Top of Mind for S&P 500 Since the Iran Shock — Who Wins When It Fades?

Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript
Top of Mind for S&P 500 Since the Iran Shock — Who Wins When It Fades?
We ran the correlation of Quant Insight’s SPY macro factor exposures to SPY’s return since Feb 27th. The results tell a clear story of what is top of mind for US risky assets.
- Rate vol is the #1 signal
Higher CB QT Expectations (1y5y swaption vol) has a −92% correlation to SPY returns. The market isn’t just worried about rate levels — it’s worried about rate uncertainty. This is the dominant headwind.
- No sustained rally without lower real yields
Higher real rates at −75% correlation.
- The Growth anchors: Higher GDP Nowcast & steeper curve
Growth signals (GDP Nowcast +89%, 5s30s curve +86%) tell you what the market wants to see.
So who wins if the Iran shock dissipates?
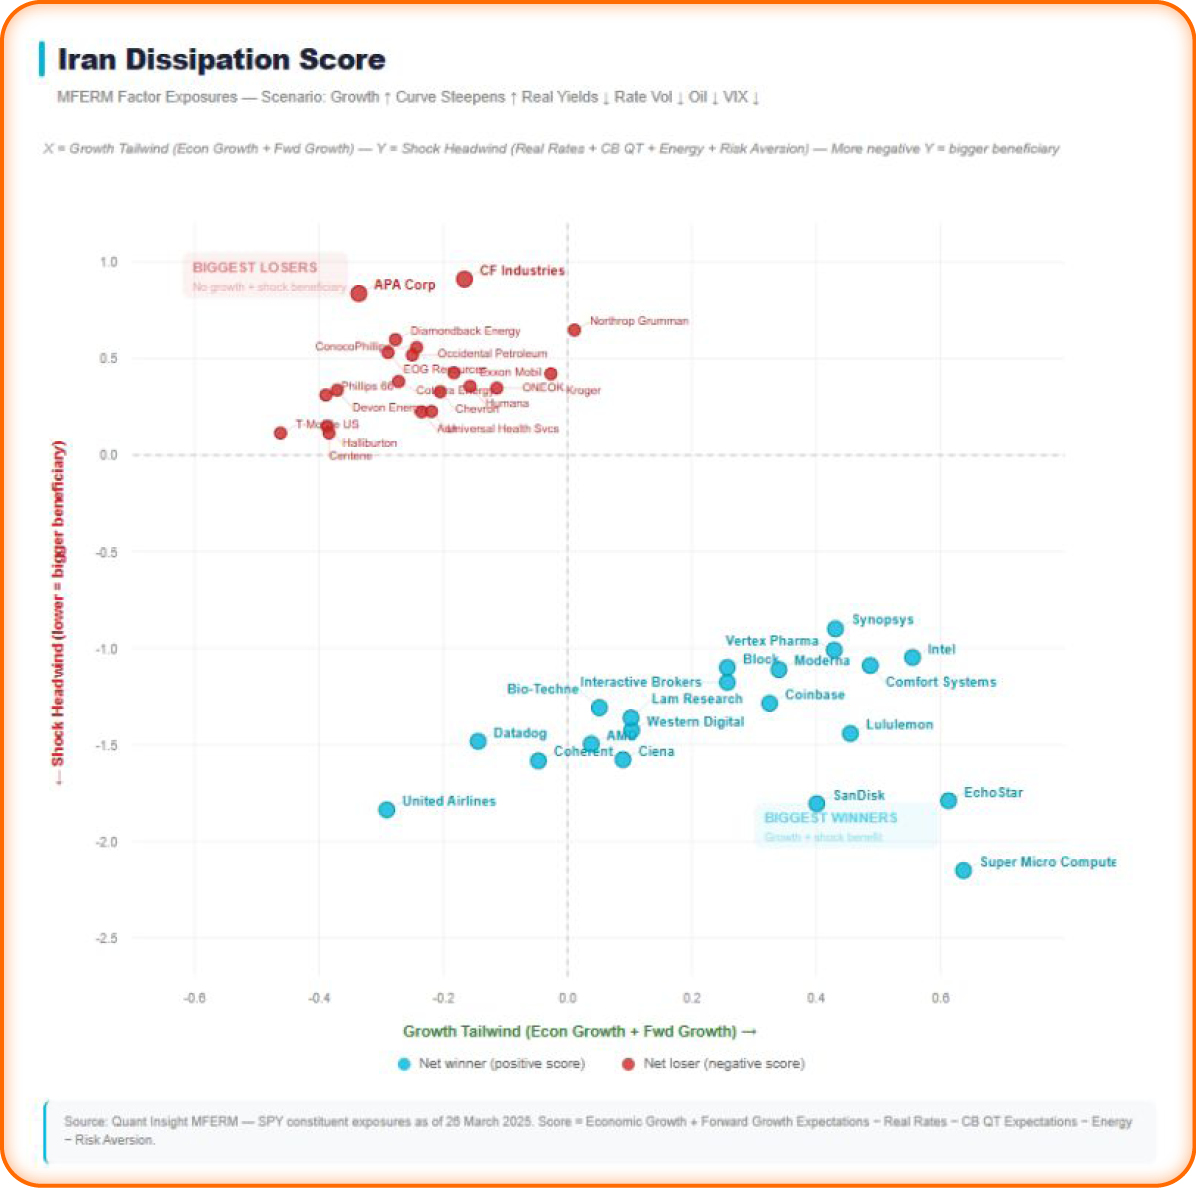
Continue reading our analysis by downloading the PDF below
Related Articles
Underweight Tech. Still Long AI
Small Caps vs Big Tech: The Rates Problem, Dissected
Credit Widened 55bp. Equities Are Only Now Listening
Oil Spike: Which S&P 500 Sectors Were Actually Macro?