Same framework. Different factor. Opposite risk signal.

Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript
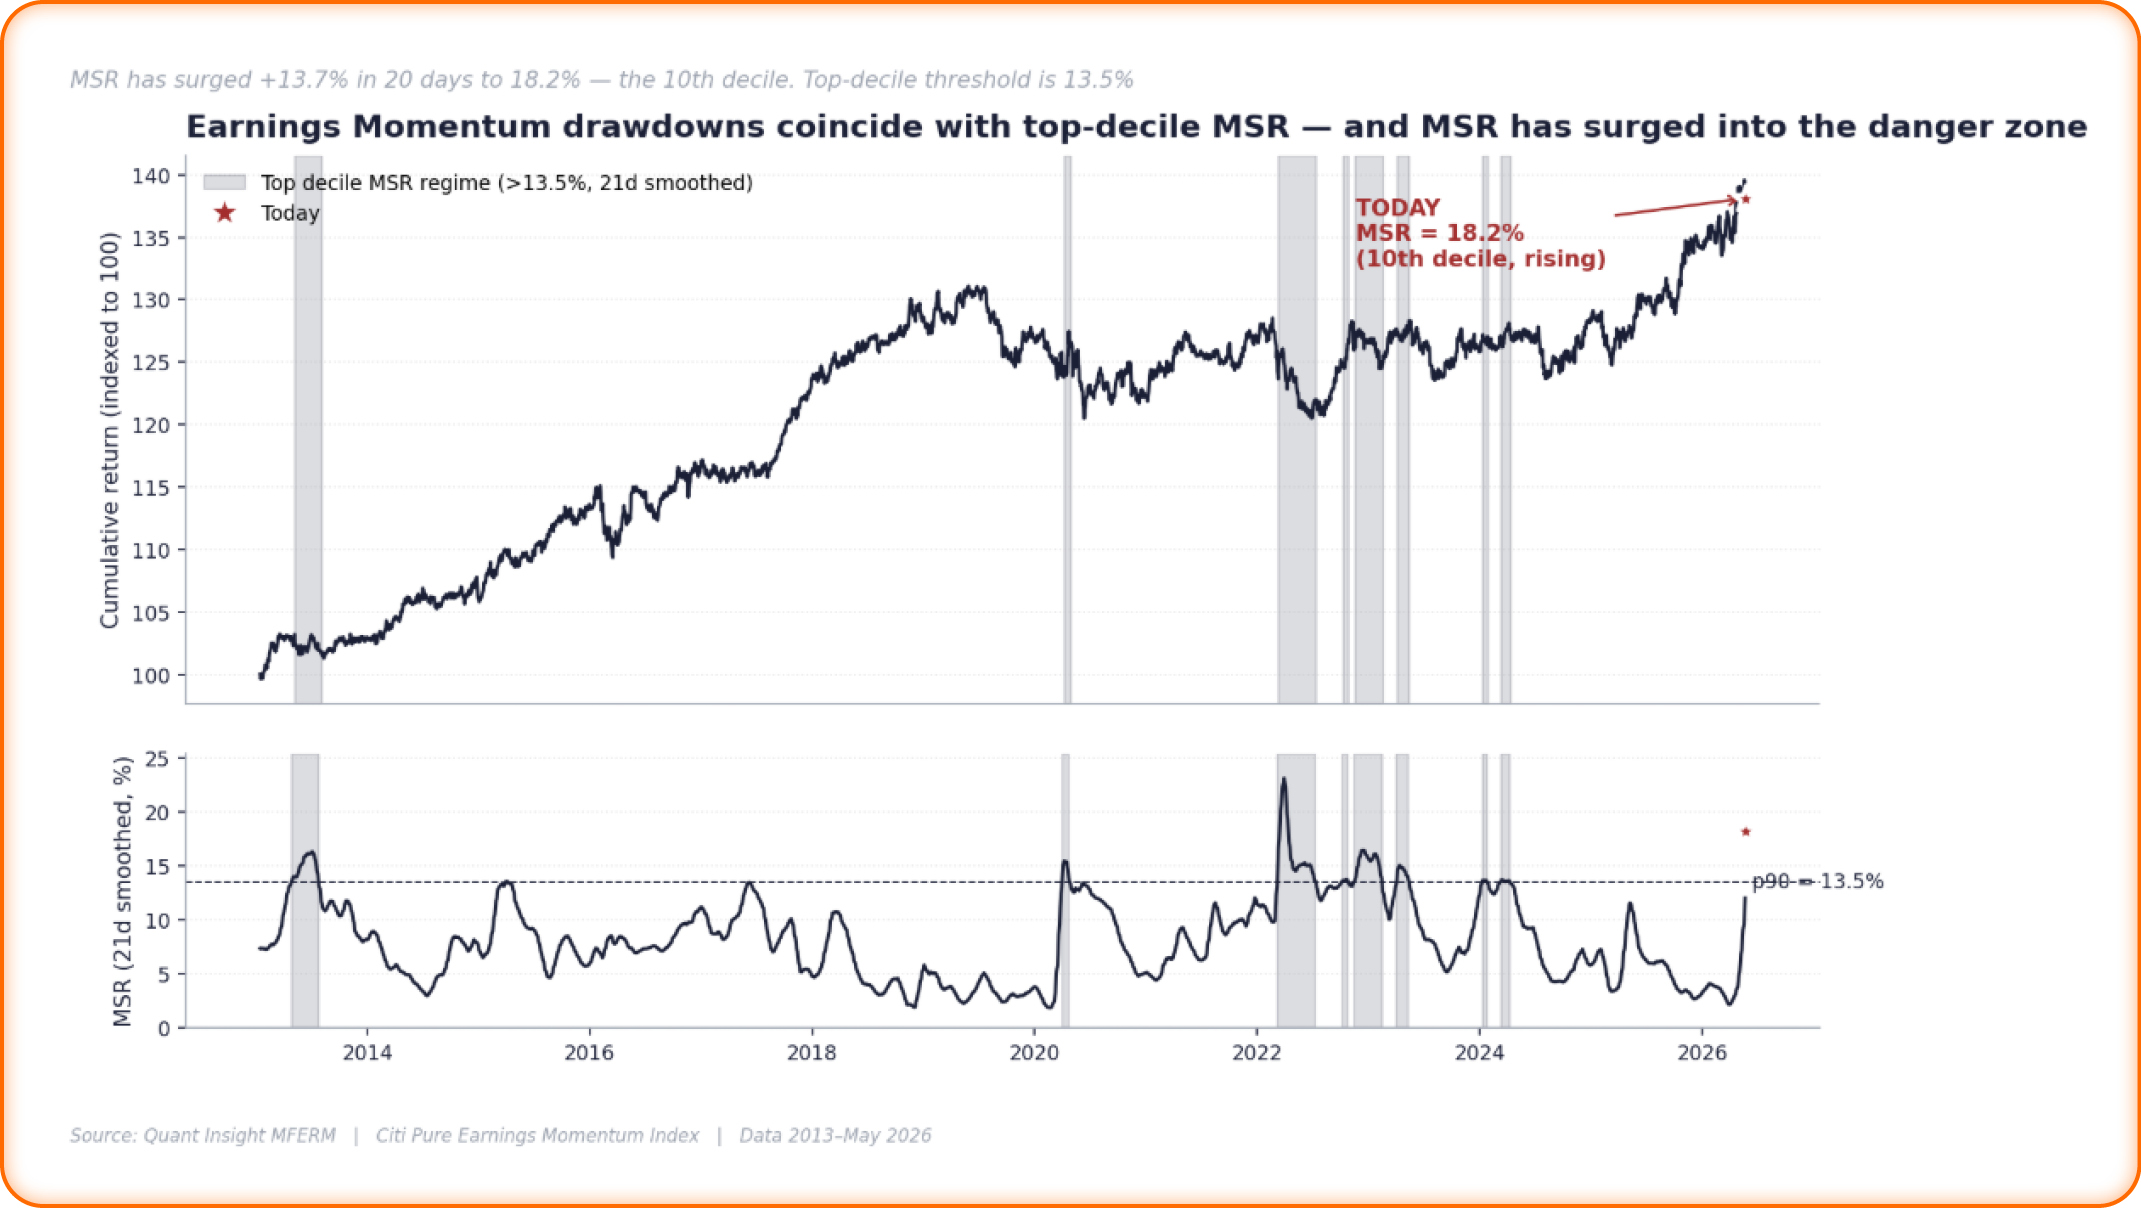
Same framework. Different factor. Opposite risk signal.
Two weeks ago, Qi flagged drawdown risk in Momentum via MSR.
Today the same framework is flagging a different factor — Earnings Momentum — but for the opposite reason.
MSR measures how much of a factor’s return variance is being explained by macro. But different factor archetypes are vulnerable in different MSR regimes.
For Price Momentum, low MSR is the fragility zone. Macro influence fades, idiosyncratic price action dominates, crowding builds in the winners — and the next macro shock can unwind the trade.
For Earnings Momentum, the risk is the other way around.
Continue reading our analysis by downloading the PDF above
Related Articles
After The Blue Sweep, The AI Risk Isn't In The Chip. It's In The Build-Out.
Underweight Tech. Still Long AI
Small Caps vs Big Tech: The Rates Problem, Dissected
Credit Widened 55bp. Equities Are Only Now Listening