Momentum is heading into a higher vulnerability regime.

Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript
Momentum is heading into a higher vulnerability regime.
Quant Insight’s MFERM model decomposes asset risk into macro and idiosyncratic components. The ratio of the two — Macro Share of Risk — has fallen from 13.4% to 6.8% on Citi’s Pure Momentum index over the last 20 sessions.
That is a bottom 4% 20-day contraction over 11 years.
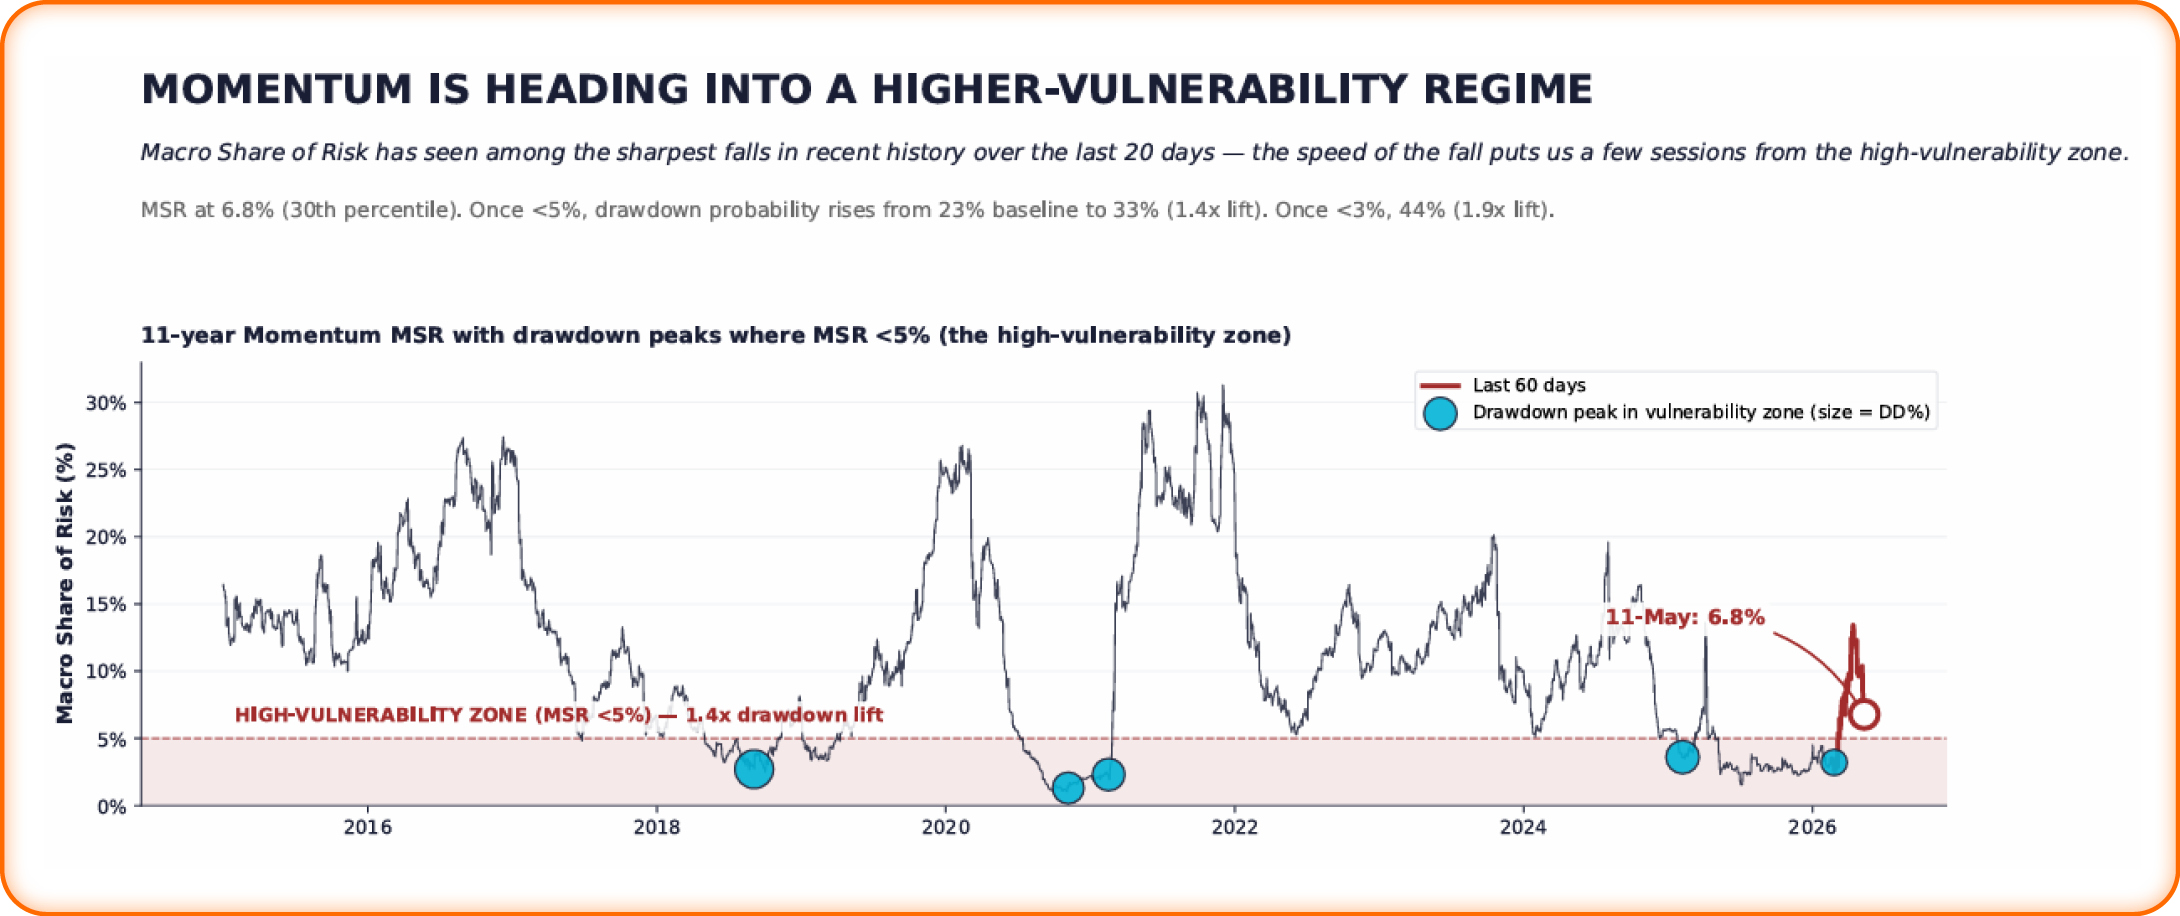
The macro footprint in Momentum is draining out of the price.
Why it matters:
- MSR <5%: drawdown probability rises from 23% baseline to 33%
- MSR ≤3%: drawdown probability rises to 44%
- MSR >20%: drawdown probability falls to 9%
The relationship is monotonic: the lower MSR goes, the wider the return distribution becomes...
This matters for the live debate on how to hedge Momentum.
Continue reading our analysis by downloading the PDF above
Related Articles
After The Blue Sweep, The AI Risk Isn't In The Chip. It's In The Build-Out.
Underweight Tech. Still Long AI
Small Caps vs Big Tech: The Rates Problem, Dissected
Credit Widened 55bp. Equities Are Only Now Listening
Related Articles