Oracle. The credit signal moved first.

Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript
Oracle. The credit signal moved first.
September 2025. MFERM flagged Oracle’s rising corporate credit sensitivity before the $18bn bond priced. Before the street downgrades. Before the consensus caught up.
Not a prediction. A measurement.
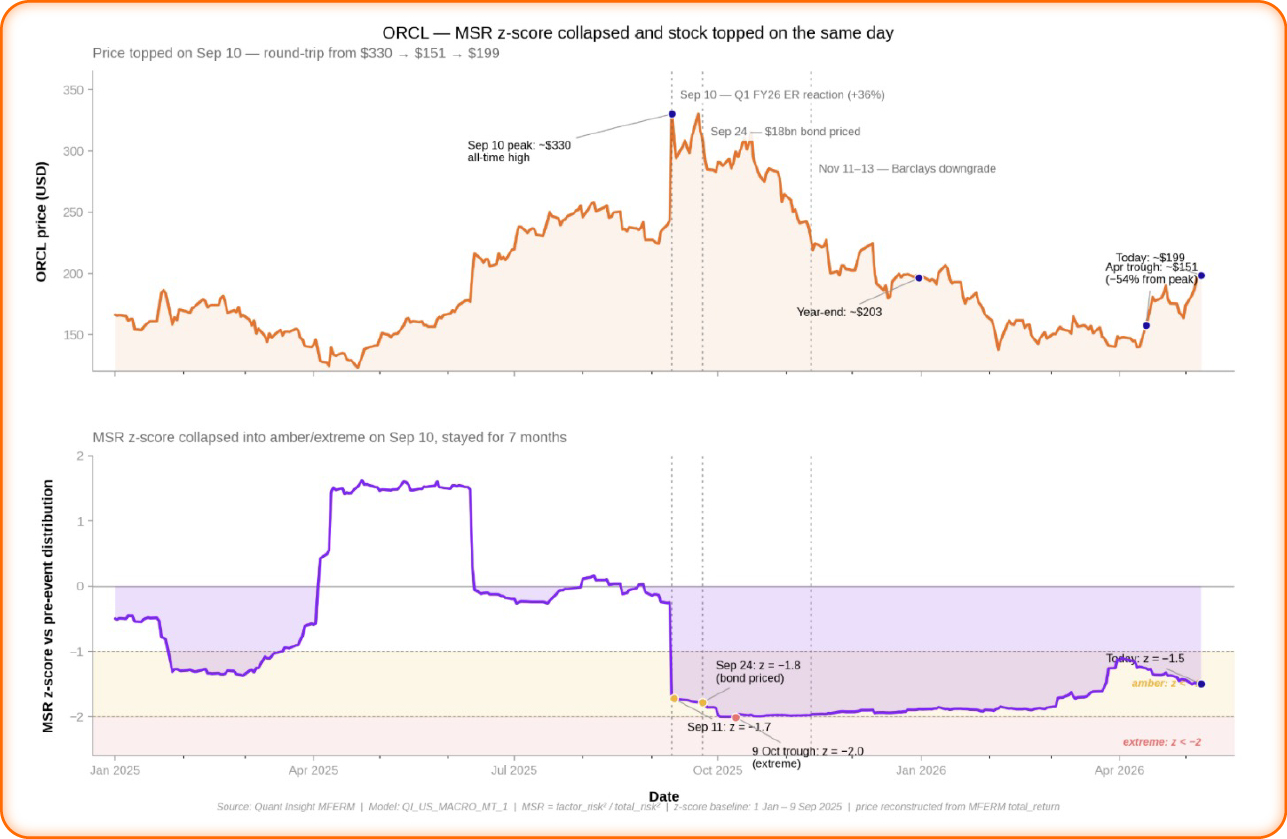
On Sep 10, Oracle reported blowout earnings. The stock hit $330, an all-time high. Two weeks later, Oracle priced $18bn of debt, one of the first mega-cap tech names to fund AI capex through bond markets rather than free cash flow.
Seven weeks after that, Barclays downgraded. The stock was already rolling over. The round trip: $330 to $151, down 54%.
What MSR was telling you
The same day earnings hit, Qi’s Macro Share of Risk collapsed to a z-score of -1.7. Idiosyncratic risk was overwhelming macro in the vol mix; the condition we associate with macro complacency. A stock priced on fundamentals alone, blind to building macro risk.
Continue reading our analysis by downloading the PDF above
Related Articles
After The Blue Sweep, The AI Risk Isn't In The Chip. It's In The Build-Out.
Underweight Tech. Still Long AI
Small Caps vs Big Tech: The Rates Problem, Dissected
Credit Widened 55bp. Equities Are Only Now Listening