Underweight Tech. Still Long AI

Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript
Last week was hard for growth and AI-heavy portfolios. If your fund lagged its benchmark, these are probably the questions you may be asking.
Here is what our cross-sectional model (MXS) shows.
WHY AI EXPOSURE IS MEASURABLE
The theme resolves into a small number of macro factors, each for an intuitive reason:
• Credit spreads; the build-out is increasingly debt-funded
• Real yields; much of the value sits in earnings far in the future
• Metals; data centres and power grids need copper
• Risk appetite; a crowded, high-conviction trade suffers first
Fundamental analysts know these links stock by stock. Macro factors measure them consistently, across every name in the book.
And they work. Since January 2024, these exposures — known the day before, explained 80% of daily moves in US semis. Market beta explained 62%.
1. WHY DID WE LAG?
• On Thursday, macro explained 58% of US stock moves
• The trigger was AI financing: capex funding concerns pushed credit wider and risk appetite lower; real yields and metals fell
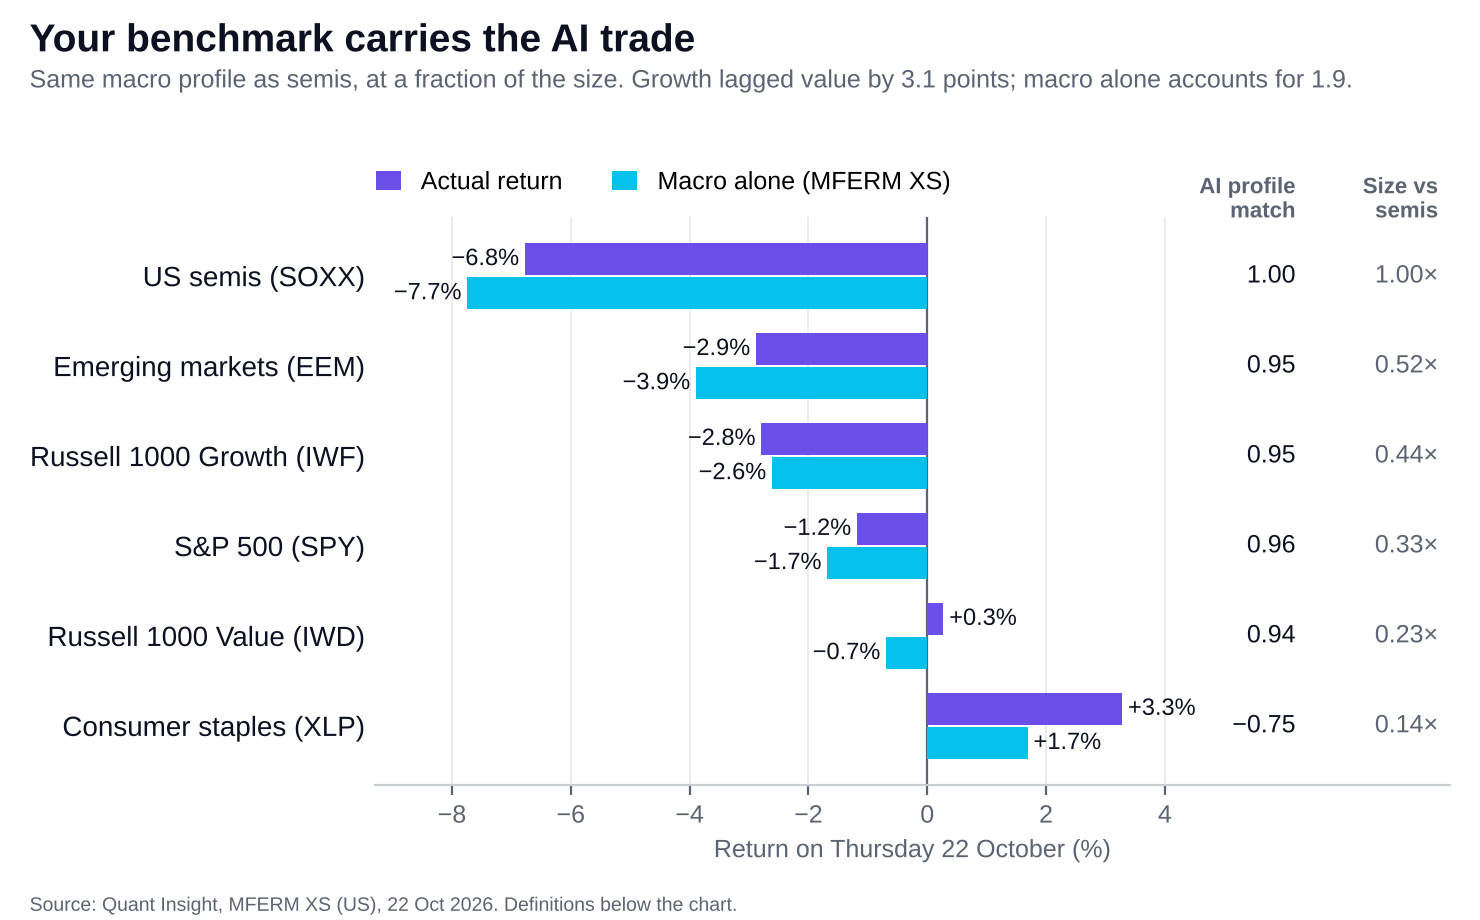
• Growth lagged value by 3.1 points. Macro alone accounts for 1.9 of them
• A style model will say growth underperformed. It won't say why
2. WAS IT OUR PICKS, OR MACRO?
• Your benchmark is already an AI trade: the S&P 500's macro exposure profile is 0.96 correlated with that of semis, at about a third of the size
• What drove your relative performance was your active exposure to that profile, over or under
• That doesn't depend on your tech weight. Power, industrials, materials and small caps carry it too
• Sector-neutral isn't AI-neutral
• Measuring it separates the stock calls from the macro bet, the story an investment committee needs
3. IS IT OVER?
• We can't say where prices go next, and no one reliably can
• But the risk tends to persist. Since January 2024, after a macro-led sell-off in semis, the chance of another within 10 sessions has been 68%, against 43% on a normal day
• This month the same pattern hit on 8, 12, 14, 16 and 22 October
4. WHAT DO WE DO ABOUT IT?
• Not necessarily sell
• For a long-term holder, the better question is which names carry the exposure, and how much
• That lets you size or hedge the AI/macro bet directly, rather than selling good stocks on a short-term macro move.
Related Articles
Underweight Tech. Still Long AI
Small Caps vs Big Tech: The Rates Problem, Dissected
Credit Widened 55bp. Equities Are Only Now Listening
Oil Spike: Which S&P 500 Sectors Were Actually Macro?