1. Equity bears need a Plan B?
2. Poor risk-reward in credit
3. Bonds vs Commodities: more to give

Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript
1.Equity bears need a Plan B?
As high beta & momentum areas of the market wobble, equity investors are once again thinking about allocations to more defensive areas of the market. Consumer Staples versus Consumer Discretionary is an obvious RV pair to consider in that scenario but, relative to macro, Staples have already moved a long way.
In market cap terms, XLP sits 1.1σ (6.3%) rich to XLY. In equal weighted terms, RSPS sits 2.4σ (8.8%) rich to RSPD. That is towards the very richest end of Qi FVG ranges.
Both models show Staples defensive properties. Higher VIX, wider credit, slower economic growth support Staples outperformance. That means macro fair value is inflecting higher for both - macro conditions support XLP / RSPS.
But markets have moved ahead of macro momentum. In short, equity bears should know these aren’t optimal levels to chase & maybe try to find alternative safe havens.
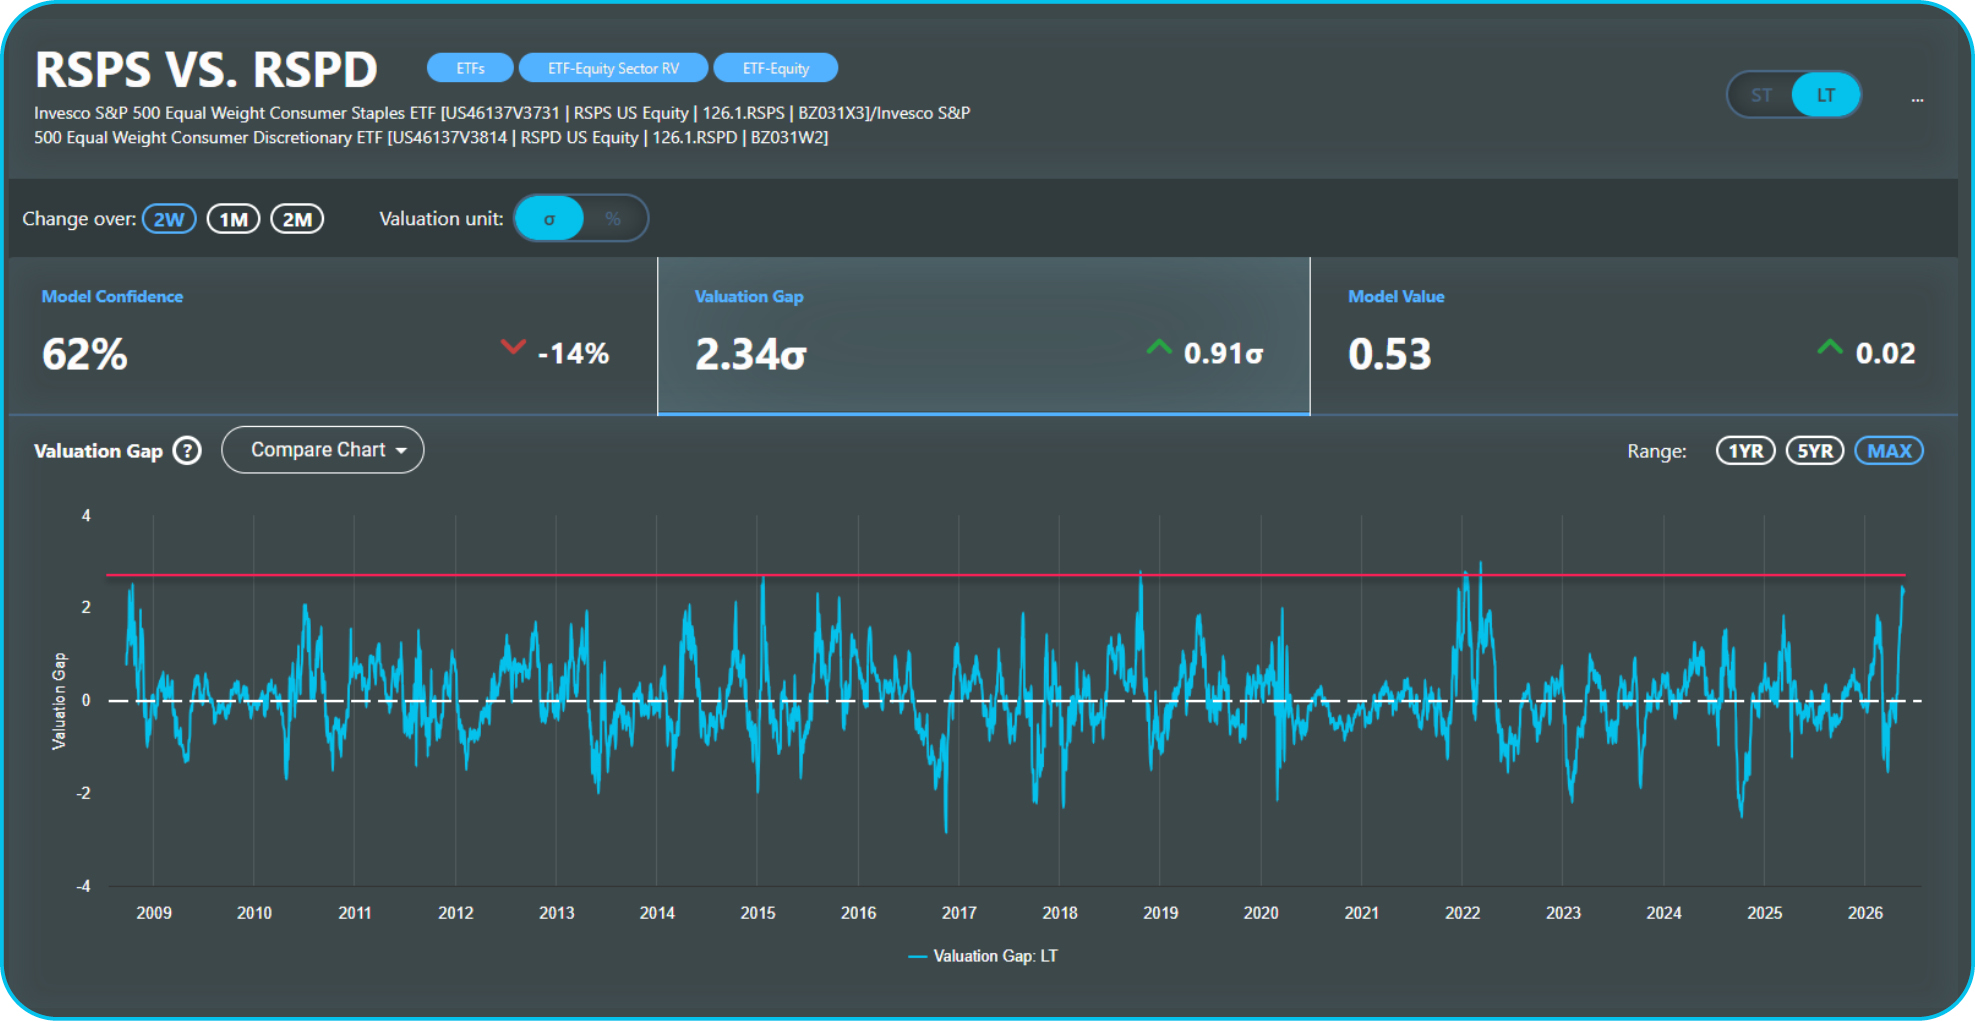
Continue reading our analysis by downloading the PDF above
Related Articles
1. Healthcare: Defensive Premium Overdone?
2. Utilities: Bond Sell-Off Casualty
3. Communications: The Leader Looks Stretched
1. Homebuilders Oversold
2. Bond Bears Pick Your Curve
3. Brazil Outruns Its Macro
1. Bullish Divergence Patterns in US Equities
2. XKL Bad News Is Getting Priced In
3. Looking to Fade the Yen? AUDJPY
1. Gold Miners: Macro Re-engagesValue
2. Rotation: Too Far, Too Fast?European
3. Credit: Value Building?